Saturday, October 24, 2026
Home Blog Page 89

ES Morning Update April 20th 2016

0

4968ceec-3724-4f51-8303-1f665f608056

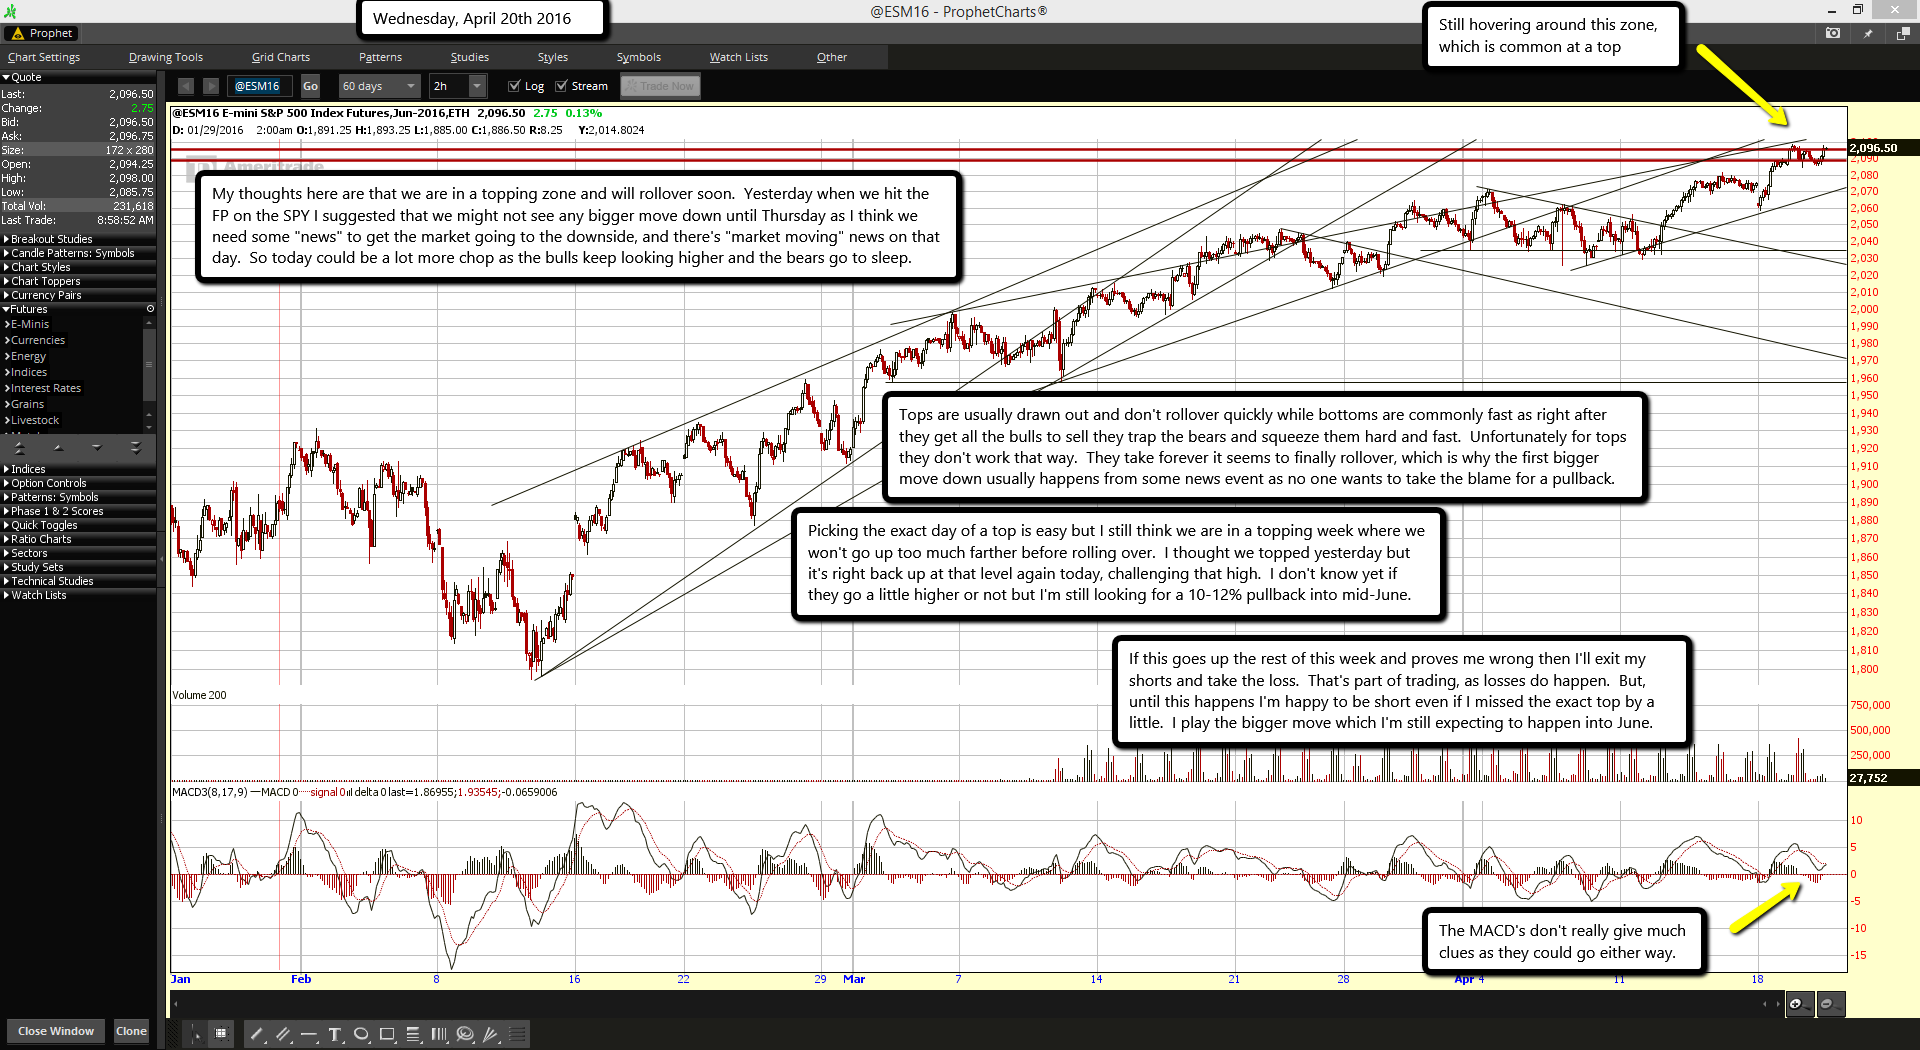
Still hovering around this zone, which is common at a top

The MACD's don't really give much clues as they could go either way.

My thoughts here are that we are in a topping zone and will rollover soon.  Yesterday when we hit the FP on the SPY I suggested that we might not see any bigger move down until Thursday as I think we need some "news" to get the market going to the downside, and there's "market moving" news on that day.  So today could be a lot more chop as the bulls keep looking higher and the bears go to sleep.

Tops are usually drawn out and don't rollover quickly while bottoms are commonly fast as right after they get all the bulls to sell they trap the bears and squeeze them hard and fast.  Unfortunately for tops they don't work that way.  They take forever it seems to finally rollover, which is why the first bigger move down usually happens from some news event as no one wants to take the blame for a pullback.

Picking the exact day of a top is easy but I still think we are in a topping week where we won't go up too much farther before rolling over.  I thought we topped yesterday but it's right back up at that level again today, challenging that high.  I don't know yet if they go a little higher or not but I'm still looking for a 10-12% pullback into mid-June.

If this goes up the rest of this week and proves me wrong then I'll exit my shorts and take the loss.  That's part of trading, as losses do happen.  But, until this happens I'm happy to be short even if I missed the exact top by a little.  I play the bigger move which I'm still expecting to happen into June.

ES Morning Update April 19th 2016

0

a3005e0e-e0fd-4b9e-b0da-6874cf90276a

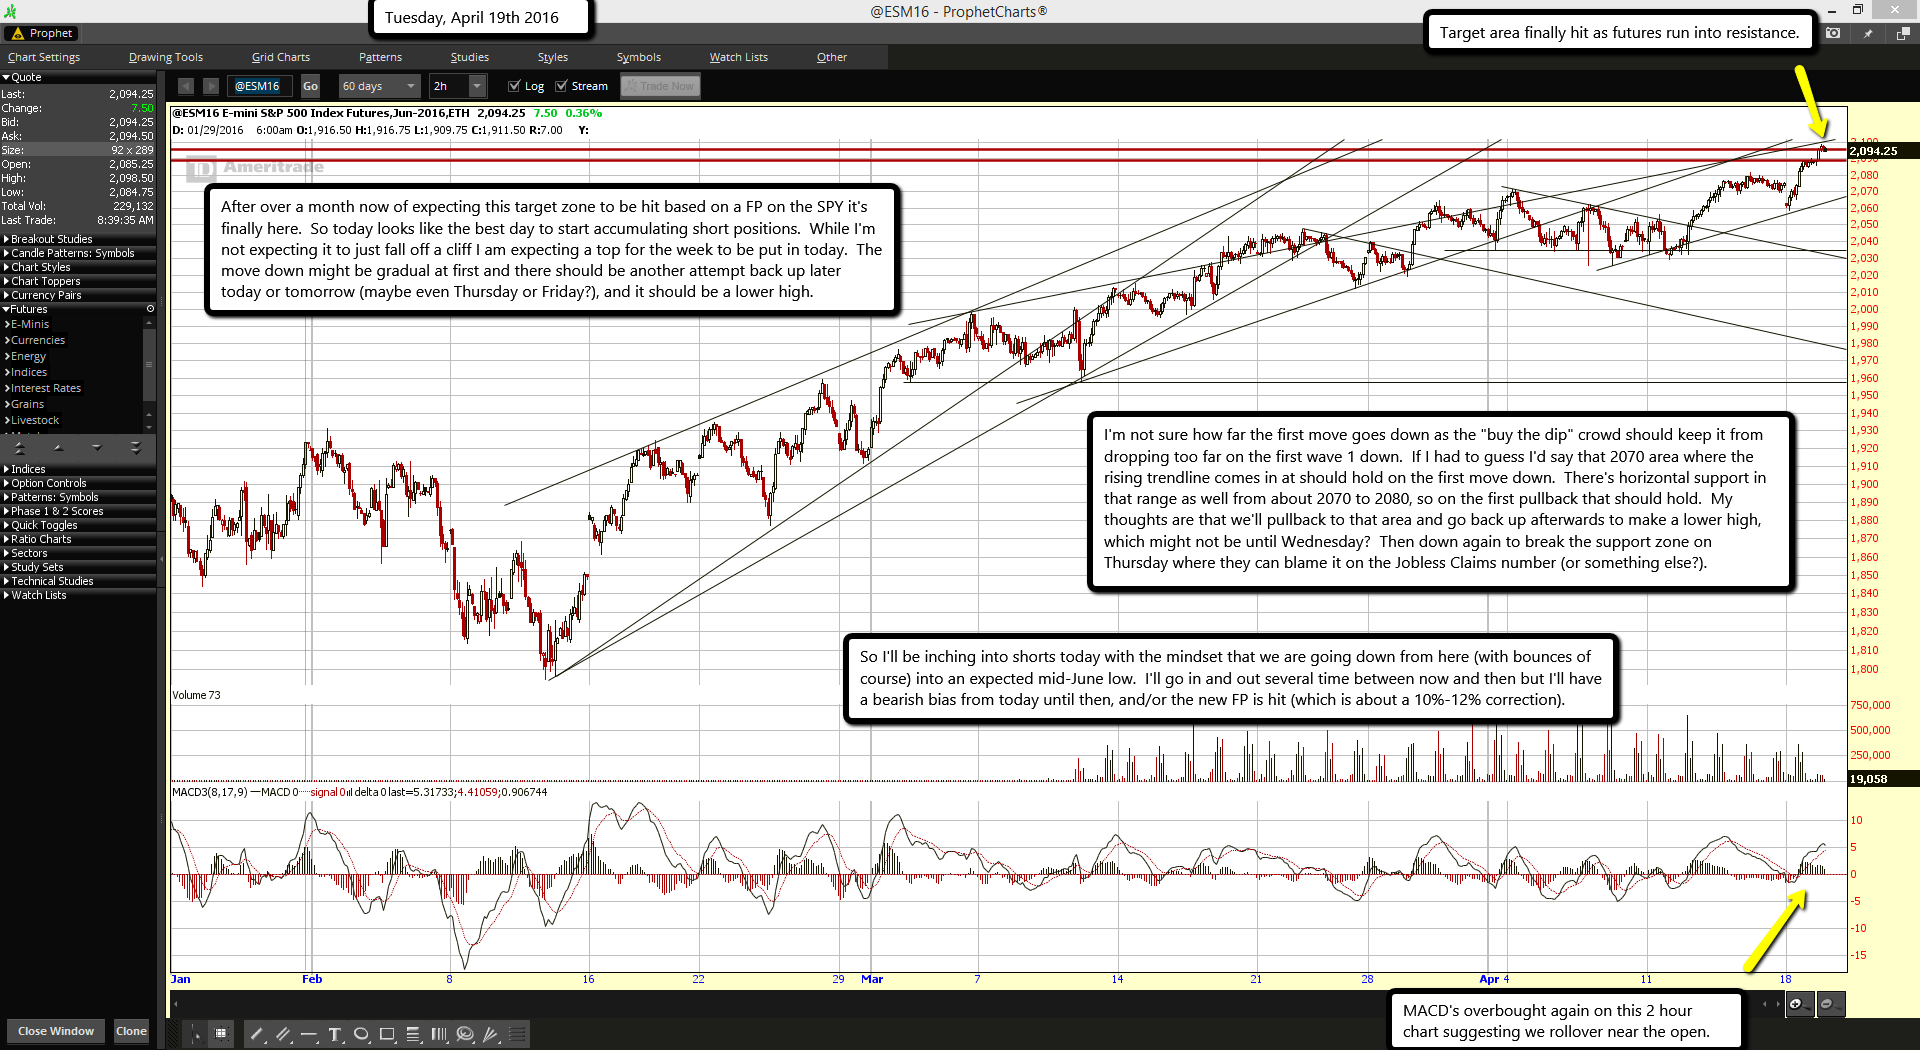
Target area finally hit as futures run into resistance.

MACD's overbought again on this 2 hour chart suggesting we rollover near the open.

After over a month now of expecting this target zone to be hit based on a FP on the SPY it's finally here.  So today looks like the best day to start accumulating short positions.  While I'm not expecting it to just fall off a cliff I am expecting a top for the week to be put in today.  The move down might be gradual at first and there should be another attempt back up later today or tomorrow (maybe even Thursday or Friday?), and it should be a lower high.

I'm not sure how far the first move goes down as the "buy the dip" crowd should keep it from dropping too far on the first wave 1 down.  If I had to guess I'd say that 2070 area where the rising trendline comes in at should hold on the first move down.  There's horizontal support in that range as well from about 2070 to 2080, so on the first pullback that should hold.  My thoughts are that we'll pullback to that area and go back up afterwards to make a lower high, which might not be until Wednesday?  Then down again to break the support zone on Thursday where they can blame it on the Jobless Claims number (or something else?).

So I'll be inching into shorts today with the mindset that we are going down from here (with bounces of course) into an expected mid-June low.  I'll go in and out several time between now and then but I'll have a bearish bias from today until then, and/or the new FP is hit (which is about a 10%-12% correction).

ES Morning Update April 18th 2016

0

020a0449-9a67-4dcd-8fc6-84c9ce7de414

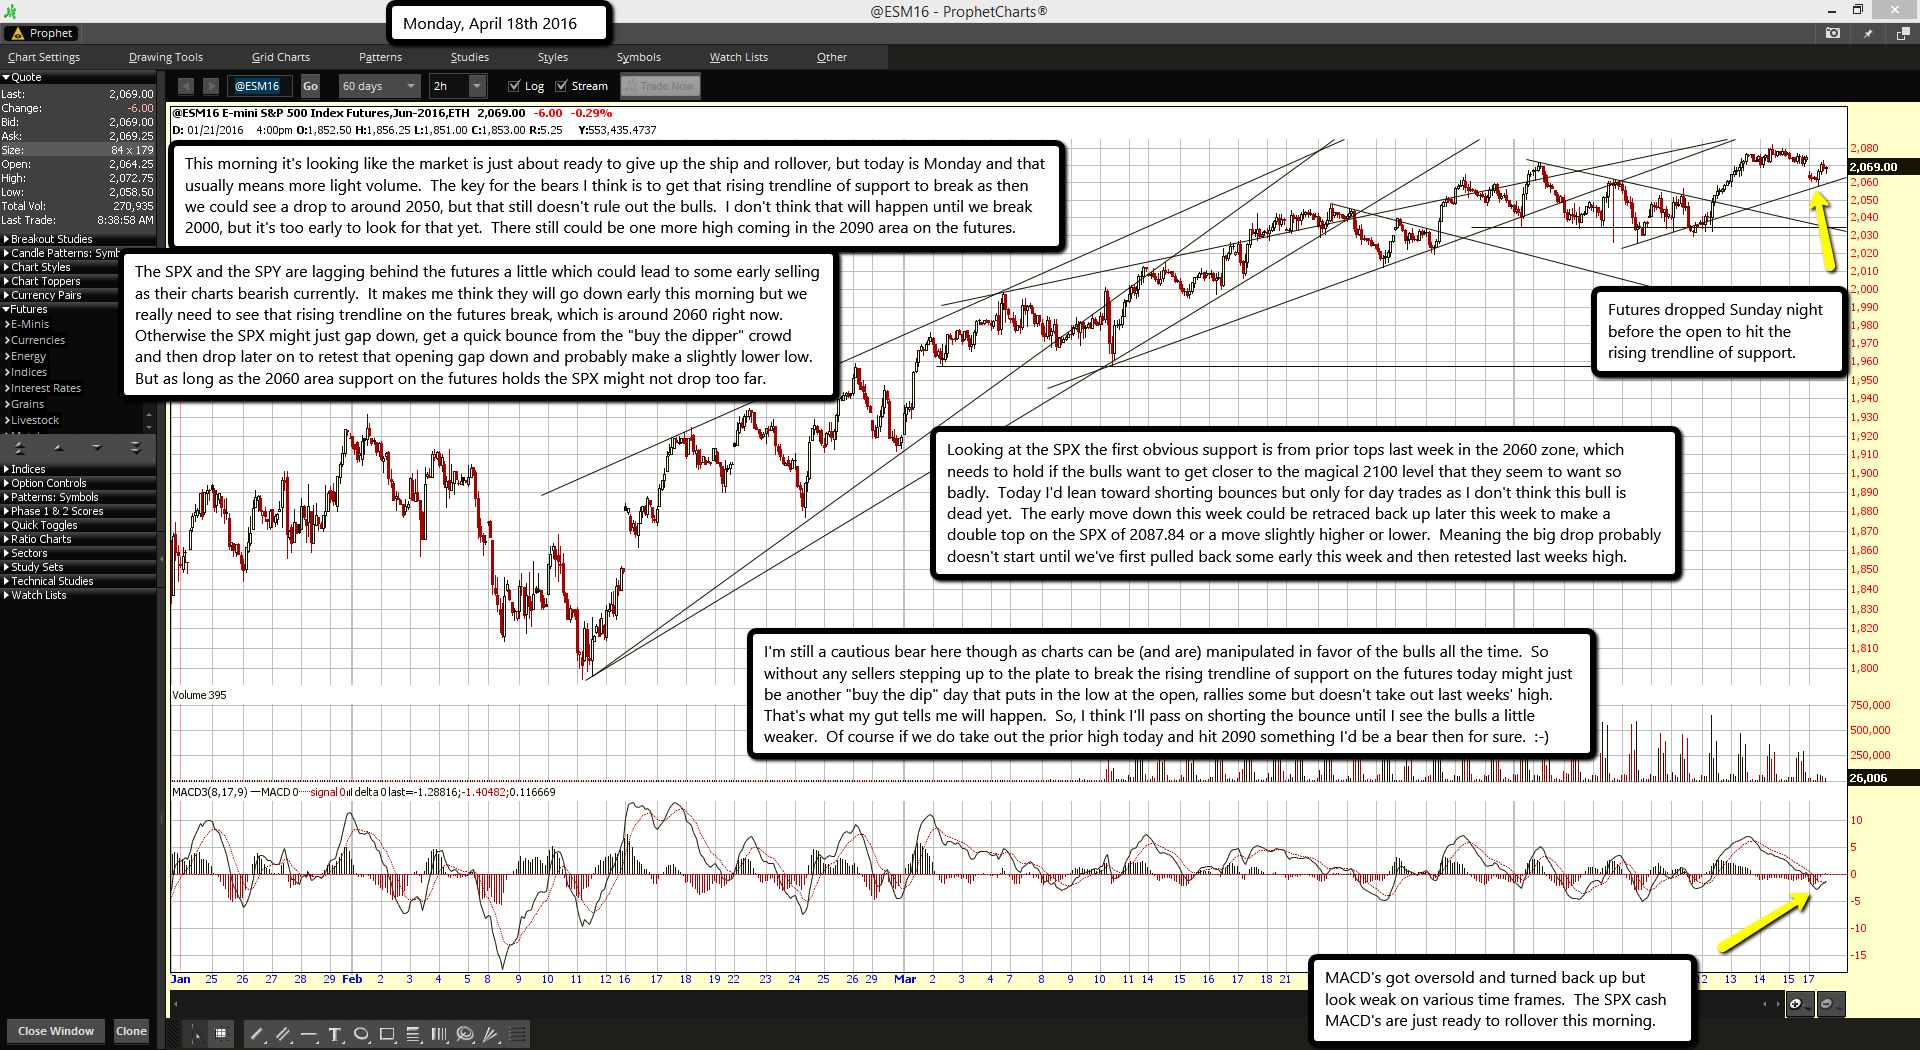
Futures dropped Sunday night before the open to hit the rising trendline of support.

MACD's got oversold and turned back up but look weak on various time frames.  The SPX cash MACD's are just ready to rollover this morning.

This morning it's looking like the market is just about ready to give up the ship and rollover, but today is Monday and that usually means more light volume.  The key for the bears I think is to get that rising trendline of support to break as then we could see a drop to around 2050, but that still doesn't rule out the bulls.  I don't think that will happen until we break 2000, but it's too early to look for that yet.  There still could be one more high coming in the 2090 area on the futures.

The SPX and the SPY are lagging behind the futures a little which could lead to some early selling as their charts bearish currently.  It makes me think they will go down early this morning but we really need to see that rising trendline on the futures break, which is around 2060 right now.  Otherwise the SPX might just gap down, get a quick bounce from the "buy the dipper" crowd and then drop later on to retest that opening gap down and probably make a slightly lower low.  But as long as the 2060 area support on the futures holds the SPX might not drop too far.

Looking at the SPX the first obvious support is from prior tops last week in the 2060 zone, which needs to hold if the bulls want to get closer to the magical 2100 level that they seem to want so badly.  Today I'd lean toward shorting bounces but only for day trades as I don't think this bull is dead yet.  The early move down this week could be retraced back up later this week to make a double top on the SPX of 2087.84 or a move slightly higher or lower.  Meaning the big drop probably doesn't start until we've first pulled back some early this week and then retested last weeks high.

I'm still a cautious bear here though as charts can be (and are) manipulated in favor of the bulls all the time.  So without any sellers stepping up to the plate to break the rising trendline of support on the futures today might just be another "buy the dip" day that puts in the low at the open, rallies some but doesn't take out last weeks' high.  That's what my gut tells me will happen.  So, I think I'll pass on shorting the bounce until I see the bulls a little weaker.  Of course if we do take out the prior high today and hit 2090 something I'd be a bear then for sure.  🙂

ES Morning Update April 15th 2016

0

b4d3b395-8cf1-4552-87cc-2bde34ae1532

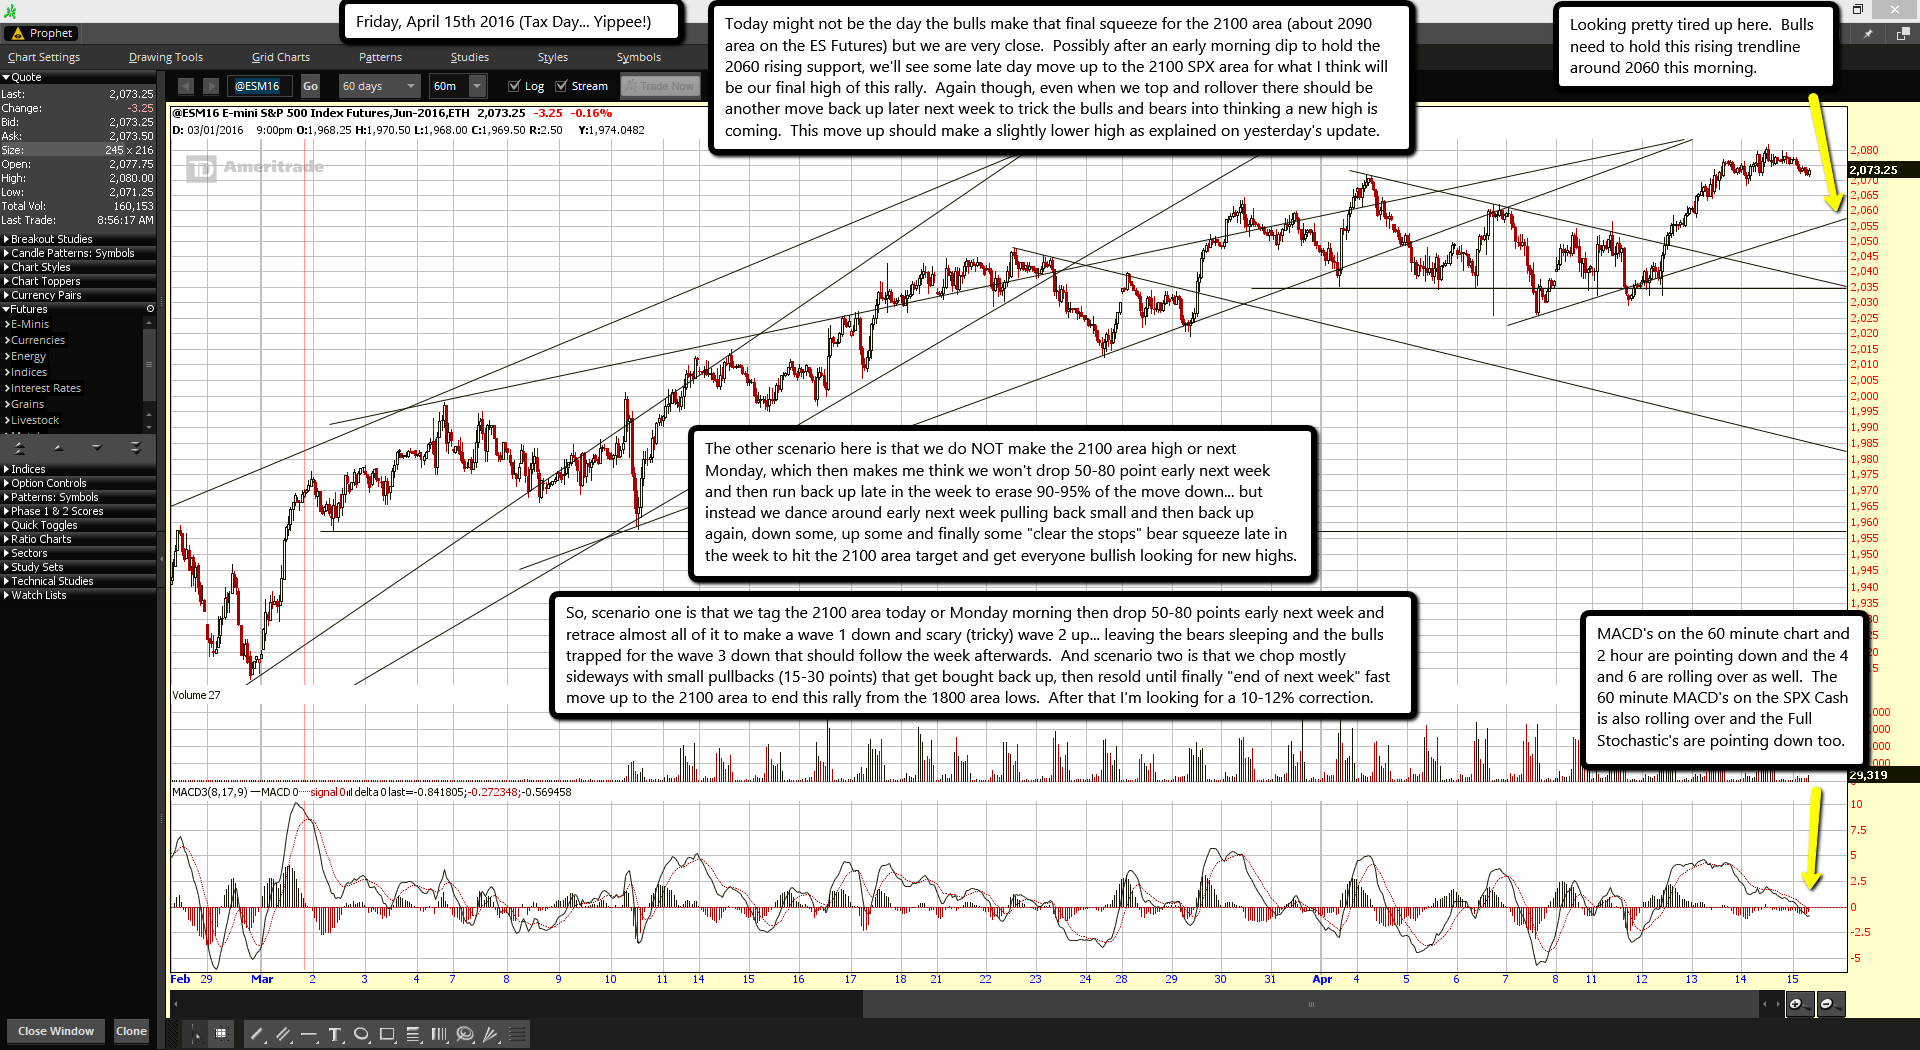
Looking pretty tired up here.  Bulls need to hold this rising trendline around 2060 this morning.

MACD's on the 60 minute chart and 2 hour are pointing down and the 4 and 6 are rolling over as well.  The 60 minute MACD's on the SPX Cash is also rolling over and the Full Stochastic's are pointing down too.

Today might not be the day the bulls make that final squeeze for the 2100 area (about 2090 area on the ES Futures) but we are very close.  Possibly after an early morning dip to hold the 2060 rising support, we'll see some late day move up to the 2100 SPX area for what I think will be our final high of this rally.  Again though, even when we top and rollover there should be another move back up later next week to trick the bulls and bears into thinking a new high is coming.  This move up should make a slightly lower high as explained on yesterday's update.

The other scenario here is that we do NOT make the 2100 area high or next Monday, which then makes me think we won't drop 50-80 point early next week and then run back up late in the week to erase 90-95% of the move down... but instead we dance around early next week pulling back small and then back up again, down some, up some and finally some "clear the stops" bear squeeze late in the week to hit the 2100 area target and get everyone bullish looking for new highs.

So, scenario one is that we tag the 2100 area today or Monday morning then drop 50-80 points early next week and retrace almost all of it to make a wave 1 down and scary (tricky) wave 2 up... leaving the bears sleeping and the bulls trapped for the wave 3 down that should follow the week afterwards.  And scenario two is that we chop mostly sideways with small pullbacks (15-30 points) that get bought back up, then resold until finally "end of next week" fast move up to the 2100 area to end this rally from the 1800 area lows.  After that I'm looking for a 10-12% correction.

In Verizon Strike, Blue-Collar Stress Hits the Sidewalks

0

By contrast, the wireless business, which is largely not unionized and where wages and benefits for rank-and-file workers are lower on average, is booming and highly profitable. Over the last few years, Verizon’s wireless business has consistently grown at least 7 percent a year, whereas its wireline business has shrunk slightly — in the last year, about 2 percent.

Striking workers outside a Verizon office in Albany on Wednesday.

At the same time, Verizon’s wireless margins are the highest in the industry. More than 40 cents of every dollar of revenue on the wireless side becomes cash flow.

Verizon’s strategic decisions reflect these diverging fortunes. In the last few years it has reduced investments in its wireline operations, even selling operations in California, Florida and Texas last year for $10.54 billion to Frontier Communications.

“At this point it’s treating wireline as a sort of cash cow rather than something to be invested in heavily, whereas wireless is where the future growth is,” said Jan Dawson, an independent technology analyst for Jackdaw Research.

Verizon has placed a big bet on the future of the wireless business. In 2013, Verizon Communications paid $130 billion to take full control of Verizon Wireless, in which it had previously shared ownership with Vodafone of Britain.

Yet these broad trends obscure some of the ways that Verizon could sustain and expand good-paying work even on the wireline side. Foremost is Fios, widely regarded as state of the art when it comes to broadband networks, and which the union and the company agree can serve as a foundation for sustaining desirable jobs.

But Verizon remains ambivalent about Fios. In 2004 the company pledged to lay fiber that could serve as many as 18 million homes. It fulfilled that plan according to its own measure, but has shown little desire in moving much beyond it, leaving several million households with little hope of getting access to the network. Until Verizon announced on Tuesday that it would be making Fios available throughout Boston, it had been several years since the company had committed itself to a major expansion.

Ian Olgeirson, an analyst at the media research firm SNL Kagan, said one reason for this reluctance to expand is that the rising price of television programming has put pressure on margins for video, which makes the economics of the entire fiber optics investment less attractive.

Still, there continues to be great demand for the broadband service, where margins are quite high. And while companies that invest in fiber optics like to see good returns on multiple services rather than just one to justify the expense, Mr. Olgeirson notes that some of Verizon’s competitors have not been deterred by this issue.

“You do see evidence of a little more enthusiasm for the wireline business at AT&T,” Mr. Olgeirson said.

Close to 36,000 Verizon workers on the East Coast have gone on strike after the company and two unions failed to reach an agreement on Wednesday. This is one of the largest strikes in recent years.

Given the potential social benefits of a broadband expansion — in terms of both jobs for those working on the network and opportunity for those using it — many experts see a rationale for a government role in at least nudging the process forward, even if the economics are too challenging for private carriers to undertake on their own. But this has not been forthcoming either.

“The F.C.C. doesn’t have an effective policy to build out broadband in the U.S.,” said Jeffrey Keefe, a professor emeritus at the Rutgers School of Management and Labor Relations, who has studied the telecom industry for decades. “Fios is a state-of-the-art broadband network. The F.C.C. has not provided the appropriate incentives.”

The two unions — the second is the International Brotherhood of Electrical Workers — have made no secret of their intention to also open a political front in the dispute. After the New York City government audited Verizon’s performance in building out its fiber optic network there, union leaders asked the City Council to hold hearings.

The unions also procured a letter from 14 mayors about the fiber optic issue and one from 20 United States senators urging Verizon to act as a “responsible corporate citizen” and negotiate fairly with its workers.

“The purposes of the strike are to build public support for the workers and to put pressure on the politicians and the regulators to put pressure on Verizon to settle this thing,” Professor Keefe said.

Even as the unions seek to build support from outside, they argue internally that there are several categories of jobs that could sustain middle-class lifestyles if the company were willing to think about them differently. One of the major points of contention between Verizon and its unions are call centers. The company currently outsources some of its customer service and sales calls to centers in lower-cost regions of the United States, and it is proposing rule changes that would allow it to do more of this.

But the cost savings that outsourced call centers appear to offer often prove illusory. Rosemary Batt, a professor at the ILR School of Cornell University who has extensively studied the moving of service work to call centers, says turnover is lower and performance and customer satisfaction are substantially higher when the work is done in-house.

“There are real opportunities to increase revenue by bundling and packaging different products,” she said, giving an example. “But you need a more sophisticated work force that’s trained and committed to the company to do that well. Outsourcing is penny-wise but pound-foolish.”

To be sure, the company is hardly oblivious to the good-jobs question. It is not seeking wage concessions, and officials there express genuine enthusiasm at the economic benefits that Fios confers on its workers. Tami Erwin, president of Verizon’s consumer and mass business unit, emphasized in an interview that the Boston expansion would mean a lot of “great high-paying work.”

But despite that expansion, the company’s overall posture does not appear to be intended to pursue a business model that maximizes the number of middle-class incomes it produces. Asked about the possible benefits of keeping call center workers in-house, Ms. Erwin said: “It’s my responsibility to make sure we’ve created an environment where people have the right tools, the right resources. If we do that, it doesn’t matter whether they’re a contractor or an employee.”

Correction: April 13, 2016 An earlier version of this article misstated the day of Verizon’s announcement that it would expand Fios service in Boston. It was Tuesday, not Monday.

Source link

Texas ag chief investigated after ‘Jesus shot’ treatment

0

FILE - In this June 18, 2015 file photo, Texas Agricultural Commissioner Sid Miller talks about the state’s plans to repeal a decade-old ban on deep fryers in public school kitchens, in Austin, Texas. Attorney General Ken Paxton has been indicted for allegedly duping investors in a tech startup, and Miller reportedly used tax dollars to travel to obtain a so-called “Jesus shot” supposedly offering long-term relief from pain. So far, fellow Republicans are all but ignoring the troubles. (Eric Gay, File/Associated Press)

AUSTIN, Texas — Public corruption investigators in Texas confirmed Wednesday they are looking into the state’s agriculture chief after allegations arose that he used taxpayer funds to obtain a so-called “Jesus shot” in Oklahoma, an injection marketed as curing pain for life.

Agriculture Commissioner Sid Miller becomes the second high-ranking Texas Republican to come under a criminal investigation since taking office last year. Attorney General Ken Paxton was indicted last summer on two felony counts of securities fraud.

Texas Department of Public Safety Tom Vinger said Miller is under investigation “regarding abuse of official capacity” but did not provide details about the scope.

The investigation comes a month after the Houston Chronicle revealed that Miller used taxpayer money to travel to Oklahoma last year to apparently receive the “Jesus shot” — an anti-inflammatory injection that is supposed to reduce chronic pain.

Miller is a rodeo calf-roper who last year unapologetically shared a Facebook post that suggested using a nuclear bomb on the Muslim population. He reimbursed the state more than $1,000 after being confronted by the newspaper’s findings but has declined to say whether he got the injection during the trip.

A spokesman for Miller criticized a liberal advocacy group, Progress Texas, which filed a formal complaint against Miller in wake of the newspaper report.

“Just because Progress Texas wants to score political points by sensationalizing a complaint that was filed by them doesn’t make it a criminal matter and doesn’t mean that the Texas Rangers have found any wrongdoing,” Miller spokesman Todd Smith said.

The “Jesus shot” reportedly costs $300 and is available only through Dr. John Michael Lonergan, who lost his medical license in Ohio after being convicted of felony health care and mail fraud and tax evasion.

Lyle Kelsey, executive director of the Oklahoma medical board, said Wednesday that state officials have previously raised questions about the Jesus shot and its effectiveness. But he said Lonergan has faced no disciplinary action and continues to have a valid medical license.

“We certainly wish he hadn’t chosen the term he chose to name it,” Kelsey said. “But that in itself isn’t illegal, it’s just embarrassing.”

Republicans have controlled every statewide office in Texas for two decades, and in 2014, Miller and Paxton cruised into office as part of a GOP ticket headlined by Gov. Greg Abbott and Land Commissioner George P. Bush, son of Jeb Bush.

The current Texas Democratic Party is so weak that it didn’t even run an opponent against Miller, who hired shock rocker Ted Nugent as his campaign treasurer and made repealing a ban on deep fryers in public schools one of his first official acts.

“All the facts point to breaking the law,” Progress Texas spokeswoman Lucy Stein said. “As a steward of the people’s money, Sid Miller must be held accountable for abusing his office.”

Earlier this week, the U.S. Securities and Exchange Commission filed accusations of investor fraud against Paxton, who has already pleaded not guilty to criminal charges of duping investors in a tech startup. He has said he won’t resign.

Other top Republican leaders, including Abbott, have consistently refused to comment on the troubles of their fellow state officials.

Source link

News About Obamacare Has Been Bad Lately. How Bad?

0

Couples at Evergreen Health Care in Manassas, Va., signing up for Affordable Care Act coverage last November.

Ever since passage of the Affordable Care Act, a fierce debate has been waged over whether the law would work as advertised. While advocates promised that the design of new insurance markets would transform the way consumers buy health insurance, critics warned that the new market would never succeed. Reed Abelson and Margot Sanger-Katz have had front-row seats to the debate, and the two reporters took a few minutes to discuss when — and if — the market would stabilize.

Margot: It’s been a few weeks of bad news about the Obamacare marketplaces. On Friday, we learned that UnitedHealth has decided to pull out of Obamacare marketplaces in two states. The week before, the Blue Cross and Blue Shield Association put out a paper offering not-too-subtle hints that some members were losing money. Reed, you wrote recently about how surprising stasis in the employer insurance market means we can look forward to much smaller Obamacare marketplaces than most people expected when the health law passed. And the parade of struggling start-up insurer companies has extended to Maine’s Community Health Options, one of the co-ops that had long been held up as one of the most successful. Health insurers need to submit their rates to regulators in the next few weeks — or decide to exit markets. Should we be worried about a health insurance apocalypse?

Reed: I think people have a tendency to catastrophize, especially when it comes to Obamacare. UnitedHealth, which is one of the nation’s largest health insurers, has only reluctantly embraced the new market, and the company is always held up as an example of why the sky is falling and why Obamacare is going to crash and burn: If United can’t make it, no one can.

United has only a small fraction of the individual market, but some of the Blues are also struggling. What is most troubling is the fact that many insurers are losing money. You may not sympathize much with the insurance companies — and no one does — but they have to make enough money to pay claims. Do you think those losses are temporary — or a sign that the market is fundamentally unstable and potentially unsustainable?

Margot: I think some of both. It seems clear that some insurers just made pricing mistakes. I’d include a lot of the nonprofit co-op plans that have gone belly up in that category. United may fall in that category, too, in some places. That doesn’t seem to me like a permanent problem. If everyone priced too low, they can just raise their prices in future years, and it’ll be O.K. That’s not great for middle-class people who pay their own premiums, but most people in the exchanges won’t notice a difference because of the way the subsidies work.

These markets also turned out to be more complicated than some insurers expected. Some regulatory choices didn’t go their way. And it does look as if more customers than you might expect are staying enrolled in plans for only part of the year, which makes it hard for the insurers to collect premiums. But I think they’ll probably figure it out.

Reed: But isn’t it a vicious cycle? The big players won’t stay in markets unless they can attract enough customers to make it worth their while. Those who say Obamacare is doomed argue that the premiums are just too high for people who don’t qualify for a subsidy. If you are insured and relatively healthy, you may not feel as if the coverage is a good deal. The deductibles are steep, meaning you end up paying for a lot of your care before you see the first dollar of coverage, and you can’t always see your choice of doctor.

The result is that the market could be too small and therefore too volatile to attract mainstream insurers like United.

How do you solve that?

Margot: Well, it seems clear that you need some competition in every market to keep prices low. But maybe we don’t need the big carriers to play everywhere. As you noted, United barely showed up in the exchanges in the first place, and customers in most markets still have a lot of choices. The Medicaid-managed care plans seem to be having some success in this market, so maybe they will be a big part of the exchange mix.

I also think it’s worth looking at the states where things are going well and the insurers are making money: California, Vermont, Washington. Those state exchanges made some different regulatory choices early on that got more people into the new markets right away, so their markets stabilized more quickly.

Reed: You’re right that you may not need the established players for the market to work. The market may not look the way we thought it would, with the same insurers and same characteristics as the employer market. But one of the reasons insurers are leaving is because of the market’s instability. There’s tremendous churn in this market, with most people switching plans every year to try to find a cheaper alternative.

I’m not sure I know what the business model is for an insurer, if the expectation is that you’re going to keep your customers for only a year. It makes achieving long-term goals like keeping people healthier and focusing on preventive measures much harder because there may be no payoff for the insurer.

Margot: Yes, I think this is one of the contradictions of the Affordable Care Act’s design. The whole idea was that competition between the insurance companies would help to hold down prices, the way it does for, say, electronics or groceries. In order for that system to work, you need people to actually switch plans if their plan starts charging more than the competition. The fact that people are actually switching seems like a sign that this market is functioning as it was designed. But as you point out, all that churn sure makes it hard for an insurer to make money by investing in its customers’ long-term health. But the individual market, pre-Obamacare, also had a lot of churn.

Reed: Yes, there’s always been churn, but the insurers got pretty good at figuring out which people they wanted to insure by turning away the people who were most likely to cost them the most money. They definitely figured out how to make money.

It’s easier to smooth all of this out if you insure more people. Do you think there’s opportunity to see the market increase in size? I know insurers in the early years suffered when some states allowed people to keep their existing plans. Those plans that were grandmothered, as it is called.

Margot: My sense from talking to folks in the industry is that the grandmothered plans really wrecked their early calculations. The Obama administration, responding to a political freakout about people whose plans were getting canceled in 2014, let states keep them for a few more years. The result was that healthy people tended to hold onto their old, cheaper plans, while sick people went to the exchanges. You can see how that might make the exchange market unprofitable for new entrants.

I do think the market size is a bit of a chicken-or-egg question. Your story last week on stability in the employer market did such a good job of laying this out. Everyone (including the Congressional Budget Office) expected that employers would start dropping coverage once the marketplaces were up and running. That didn’t happen. It means that Obamacare has been much less disruptive to the status quo than many people thought. But it also means that the exchange markets are smaller and probably more expensive than people thought, too. If prices keep going up, maybe they’ll never grow much. It certainly seems like everyone is cutting down their long-term estimates for exchange enrollment.

Reed: The other possibility would be to expand the pool of people who qualify for subsidies. Is that a political nonstarter?

Source link

Report: US medicine spending up 8.5 percent 2015

0

U.S. spending on prescription drugs rose 8.5 percent last year, slightly less than in 2014, driven mainly by growing use of ultra-expensive new drugs and price hikes on other medicines.

A report from data firm IMS Health estimates patients, insurers, government programs and other payers spent a combined $309.5 billion last year on prescription medicines.

The IMS Institute for Healthcare Informatics is forecasting that annual increases in U.S. prescription drug spending will slow to 4 to 7 percent through 2020, after rising around 10 percent in each of the past three years. It predicts spending will reach $370 billion to $400 billion in 2020.Report: US medicine spending up 8.5 percent 2015 photo

FILE - In this June 14, 2011, file photo, bottles of prescription drugs: Lipitor, TriCor, Plavix, Singulair, Lexapro and Avapro are displayed at Medco Health Solutions Inc., in Willingboro, N.J. U.S. spending on prescription drugs rose 8.5 percent last year, slightly less than in 2014, driven mainly by growing use of ultra-expensive new drugs and price hikes on other medicines. A report from data firm IMS Health estimates patients, insurers, government programs and other payers spent a combined $309.5 billion last year on prescription medicines. (AP Photo/Matt Rourke, File)

The totals are based on net prices paid after deducting discounts and rebates that manufacturers give to insurers and other payers. In prior years, IMS based its report list prices before those deductions.

The report comes amid growing criticism of unaffordable drug prices from patients, doctors, insurers, Congress and presidential candidates, who have pledged to rein in drug prices. Insurers have been trying to limit prices, demanding bigger discounts to cover many drugs, but have less clout on drugs with little or no competition.

Drug spending keeps growing due to factors including rising prices, fewer blockbuster drugs getting new generic competition and a 10 percent jump last year in the number of prescriptions filled, to nearly 4.4 billion. In prior years, total prescriptions dispensed edged up about 2 percent.

"We have more people with health insurance (now), and that could be a reason we're having more uptake in brand-name drug use," said Murray Aitken, the institute's executive director.

About 20 million people are newly insured as a result of the Affordable Care Act. They are mostly getting low-cost generic drugs, Aitken noted.

New brand-name drugs for cancer, hepatitis C and a number of rare diseases are being launched with staggering list prices, often exceeding $100,000 for a year or course of treatment. Meanwhile, drugmakers routinely raise prices for older brand-name drugs one or more times a year, often pushing them up 20 percent or more each year. Also, several companies have been buying rights to older drugs with limited competition, then quickly jacking up prices several times what they had been for years.

Total drug spending rose by $24.3 billion last year, with more than half of that increase spent on brand-name drugs on the market for less than two years. In 2015 alone, 43 new drugs and 30 new formulations of existing ones were launched.

Because sales of new drugs generally build slowly over several years as doctors become familiar with them, spending on those new drugs should grow even more in the coming years.

Still, the 2015 spending increase of 8.5 percent was down from the 10.5 percent jump in 2014.

"For all the headlines, drug spending growth has moderated in 2015," Aitken said.

However, it's still increasing far more than general inflation, which has been about 2 percent in recent years.

U.S. drug spending now accounts for about 40 percent of what's spent worldwide, partly because Americans pay much higher prices than people in other countries, which generally set price caps.

Patients increasingly are being squeezed by the cost of their medicines, because drug prices are rising at the same time that employers and insurers are shifting a much bigger percentage of drug and other medical costs onto workers.

Since 2010, the average patient's out-of-pocket cost has soared more than 25 percent, to $44 per prescription. For generic drugs, however, average patient cost has remained about $8.

Meanwhile, drugmakers aiming to get more patients to take their brand-name drugs have been offering discount coupons that generally reduce the patient's monthly copayment to $50 or less.

Nurse practitioners and physician assistants are writing more prescriptions, hitting a total of 576 million in 2015, more than double the number five years ago.

That's because many states have expanded their prescribing authority, particularly in areas with shortages of doctors.

Source link

Why US regulators rejected ‘living wills’ from five major banks

0

Wall Street banks might be too big to fail after all.

On Wednesday, government regulators from the Federal Reserve and the Federal Deposit Insurance Corp. rejected proposals from five out of eight of the biggest banks operating in the US that explained how they would handle operations in the event of bankruptcy and proceed without the help of public money in the event of a crisis.

The proposals, also known as “living wills,” are a regulatory requirement of the Dodd-Frank act, which was passed after the 2007-09 financial crisis in order to prevent another one from happening. Banks whose proposals did not make the grade include JPMorgan Chase, Bank of America, Wells Fargo, Bank of New York Mellon, and State Street.

They will have until Oct. 1 to fix their submissions and may face stricter regulatory measures if they do not.

“[E]ach plan has shortcomings or deficiencies, although as the letters emphasize, some firms have made more progress than others,” FDIC Vice Chairman Thomas M. Hoenig said in a statement. “Most importantly, no firm yet shows itself capable of being resolved in an orderly fashion through bankruptcy.  Thus, the goal to end too big to fail and protect the American taxpayer by ending bailouts remains just that: only a goal.”

Citigroup’s living will was the only proposal to pass muster, although regulators noted that it still had some shortcomings. Citi responded to the feedback by saying that while the bank maintains a global presence, it has become “simpler, smaller, safer and stronger” since the financial crisis.

In a statement, Wells Fargo said, “We were disappointed to learn that our 2015 resolution plan submission was determined to have deficiencies in certain areas… We understand the importance of these findings and we will address them as we update our plan by the October 1, 2016 deadline identified by the agencies. We remain dedicated to sound resolution planning and preparedness.”

The FDIC also rejected a living will from Goldman Sachs. Regulators have not looked kindly on Goldman this week. On Monday, the Department of Justice announced that Goldman will pay $5.06 billion in a settlement regarding its handling of mortgage backed-securities during the Great Recession, including $1.8 billion to be paid to underwater homeowners and impacted communities. While no individual bankers were charged with wrongdoing, the settlement is a sign that government regulators are taking stricter measures against banks’ fraudulent activity.

This is not the first time that the FDIC and Federal Reserve have found banks’ living wills lacking. In 2014, they rejected proposals from banks including Goldman Sachs and Barclays for insufficiently describing how they would enter bankruptcy without triggering a financial crisis.

Federal Reserve Chair Janet Yellen said last week that she is not concerned about what effect these so-called “too big to fail” banks could have on the US economy, saying that the policies put in place by government regulators “have greatly enhanced the safety and soundness of the banking system.”

Wall Street reform has been a focal point of this election and a major talking point for Bernie Sanders, who has built his campaign around the goal of breaking up the banks. Hillary Clinton and Ted Cruz have also made comments stating their commitment to reducing financial corruption.

Source link

Delta dumps one of the most hated airline fees

0

delta in person

Well here's something you don't hear every day: An airline is eliminating a fee.

Delta Airlines is no longer charging customers a fee to speak with an actual human being while booking flights.

In the past, the Atlanta-based airline charged travelers $25 per ticket for booking over the phone and $35 when buying at an airport.

Related: How to score the cheapest airfare this summer

"This -- and every decision we make -- is based on engaging with our customers and employees every day," said Charisse Evans, Delta's (DAL) vice president, reservation sales and customer care, in a statement.

Other airlines, including United (UAL)and JetBlue (JBLU), still charge fees for most reservations made over the phone.

Airlines have been tacking on fees to ticket prices over the years for things like extra leg room and seat assignments to help boost their revenue.

Last month, Southwes (LUV)hiked the cost of its EarlyBird Check-In fee by 20%.

Phone reservation fees have been a top complaint from travelers.

A 2014 report from Airfarewatchdog.com found that consumers rank charging for checked bags, changing or canceling a reservation, advanced seat selection and making phone reservations among the most egregious fees when flying.

Related: Which airline offers the most legroom?

Delta announced better-than-expected quarterly earnings before Thursday's opening bell with a net income of $946 million or $1.21 a share.

Source link

Shuddle, Uber for kids startup, runs out of gas

0
635962580995423279-shuddle.JPG

SAN FRANCISCO - The on-demand business model is getting more demanding.

That's certainly the experience of Shuddle, an Uber-for-kids startup that Thursday announced it would be shutting down after failing to raise another round of funding. In a note to customers, company officials said they had "worked hard to find the financial resources that would allow us to continue to grow, but ultimately could not raise the funding required to continue." April 15 is the last day of operations.

Shuddle, founded in 2014 by former Sidebar employee Nick Allen, had raised $12 million, which it had hoped to use to expand outside the Bay Area. Instead, it served to keep the company alive. Shuddle targeted busy parents who were willing to pay fares that were slightly higher than Uber and Lyft for access to drivers who had passed a rigorous company screening that valued childcare experience. The vast majority of its drivers were women.

The segmentation of the ride-hailing market has exploded since Uber stormed onto the scene. Los Angeles-based HopSkipDrive is playing in the same space as Shuddle and has raised $14 million to date. Lift Hero focuses on older riders, while Zum offers baby sitting services in addition to rides for children.

It remains unclear how these other ride companies' business models will thrive where Shuddle's did not, and generally speaking the fund-raising climate in Silicon Valley has gotten noticeably tighter in 2016 as investors want to see returns on their capital.

"This may seem like a sudden change, but the complexity of our operation made it difficult to try to wind down gradually," Shuddle CEO Doug Aley said in a statement. Among the list of company accomplishments, he cited a staff of 32, providing 65,000 rides around the Bay Area, and growing the business 50% in the past six months.

But "as we all have seen in today’s headlines, it is an extremely challenging environment for raising new capital," Aley wrote. "We worked hard with our existing investors to find new financial resources that would help us continue to grow. But, we could not raise the funding required to continue operations."

Source link

MidAmerican Energy pours $3.6B more into wind

0
635878664683750850-des.m1116wind02cg.jpg

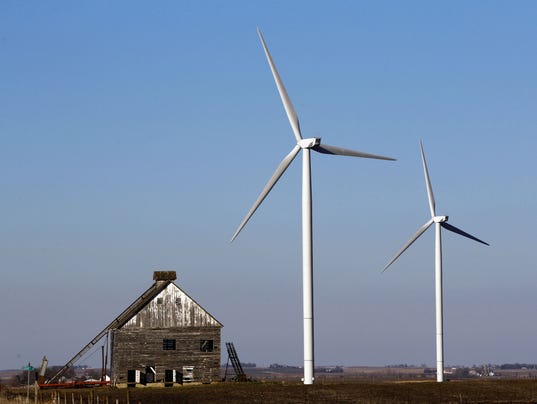
MidAmerican Energy took a giant, $3.6 billion step Thursday toward its goal of meeting all of its customers' power needs with green energy such as wind and solar.

With the investment, the Des Moines utility's largest, MidAmerican would get 85 percent of its energy from wind, CEO Bill Fehrman said Thursday at a press conference with Gov. Terry Branstad and Debi Durham, the state's economic development director.

"We have a dream to deliver 100 percent renewable energy to our customers," Fehrman said.

Officials with the Des Moines utility, already the nation's largest rate-regulated owner of wind energy, said the project would add up to 2,000 megawatts of wind generation.

The project, called Wind XI, won't increase consumers' energy bills, thanks largely to federal production tax credits that would cover the project's cost over 10 years, Fehrman said.

"For customers, the benefits are clear: clean energy produced right here in Iowa using an abundant natural resource," Fehrman said. "Unlike coal or natural gas, renewable energy has no fuel costs associated with it. Harnessing the wind is free."

MidAmerican serves 752,000 customers in Iowa, Illinois and South Dakota.

MidAmerican's announcement received resounding approval across the board, including from U.S. Sen. Chuck Grassley, Rep. Dave Loebsack, U.S.  Agriculture Secretary Tom Vilsack and state and national environmental groups.

Nathaniel Baer, energy program director at the Iowa Environmental Council, said the announcement sets the renewable energy bar higher for other Iowa and Midwest power suppliers.

"Making 100 percent renewable energy a goal starts a new discussion about how to get there. It’s an important new direction," Baer said. "It recognizes that the renewable energy sources we have in Iowa are tremendous."

The request must go to the Iowa Utilities Board for consideration. The company hopes to get board approval by mid-September.

The project, with about 1,000 turbines, wouldn't be completely constructed until 2019. The turbines' location is still under consideration.

Fehrman said the utility's shift to wind has been dramatic since 2004, the first time it invested in wind energy generation.

"We didn't have any wind in our system, and coal made up 70 percent of our generation," Fehrman said. "By the end of this year, we will have built 4,048 megawatts of wind energy across 2,020 turbines."

The company has spent $6.6 billion on wind generation over the past 12 years. It will get close to 60 percent of its energy from wind by year's end.

Even with 100 percent of its energy from renewable sources, Fehrman said the investor-owned utility has no plans to retire its coal and natural gas plants.

"During times when the wind isn’t blowing — or isn't blowing enough — our coal plants, gas plants will be picking up the slack," Fehrman said

He said the company wants to to generate as much wind energy as its customers use annually.

"We will be able to certify to our customers that at least on an annual basis — not a minute-to-minute or hour-to-hour basis — we were able to deliver to you 85 percent of energy from renewable power.

"And hopefully we’ll get to 100 percent some time down the road," said Fehrman, adding that the utility will look to solar, energy efficiency, biomass and other sources to reach its goal.

RELATED:  Solar advocates say new pricing plans will hurt progress

Robert Brown, professor of mechanical engineering and director of the Bioeconomy Institute at Iowa State University, said the utility will still need a considerable amount of fossil fuel generation to back up its wind generation.

For 100 percent renewable generation, the country needs utility-scale battery storage, smart grid improvements that can shoot renewable energy across the nation and power plants that burn biomass — plants such as perennials, Brown said.

Fehrman agreed that renewable energy storage is critical to growing green energy use.

"Battery storage is a game-changer in this renewable energy environment," he said. "The issue today is that it’s very, very expensive."

MidAmerican said no other utility has "staked out this 100 percent position."

"Our customers want more renewable energy, and we couldn’t agree more," Fehrman said.

Environmental groups applauded the investment.

"MidAmerican made clean energy history today," said Bruce Nilles, senior director for Sierra Club’s Beyond Coal Campaign. "Iowa and MidAmerican's rapid transition from dirty coal to affordable wind offers a game-changing new model for how utilities will reach 100 percent renewable energy more quickly than anyone would have predicted."

“MidAmerican’s announcement reaffirms that wind energy is affordable, reliable and strengthens our energy independence,” said Josh Mandelbaum, an attorney at the Environmental Law & Policy Center.

MidAmerican said the proposal puts the state in "a strong position to comply with carbon emissions limits." Iowa is required to reduce carbon emissions from its power plants by 42 percent under the federal Clean Power Plan, which is now being challenged in courts.

Branstad said the MidAmerican project "puts Iowa on track to be the first state in the nation to generate more than 40 percent of its energy needs from wind power — far ahead of any other state.

"Today, Iowa is the only state to have crossed the 30 percent mark,” Branstad said.

RELATED: 

Durham called MidAmerican's goal "audacious," adding that it could be a significant economic development recruitment tool.

Leaders have said wind energy in Iowa has been critical to attracting Facebook, Google and Microsoft data centers to the state. The operations are huge energy users, and the tech companies want renewable energy to be a large piece of the portfolio.

"What these publicly traded companies need to show shareholders and customers, particularly millennials, is that a large part of energy portfolio is from renewable," she said. "That's a calling card that separates Iowa from other states."

Fehrman said wind has helped make MidAmerican's energy costs seventh-lowest in the nation.

The company has wind farms in operation or under construction in 23 Iowa counties and has partnered with more than 2,400 Iowa landowners to place the turbines.

Leaders said wind power supports as many as 7,000 jobs in Iowa.

Fehrman said the new project would generate about $12.5 million per year in property tax payments, $18 million per year in landowner payments, and $48 million per year in state and local expenditures.
Source link

ES Morning Update April 14th 2016

0

79a90a42-27bf-4469-a203-b125ef1e8634

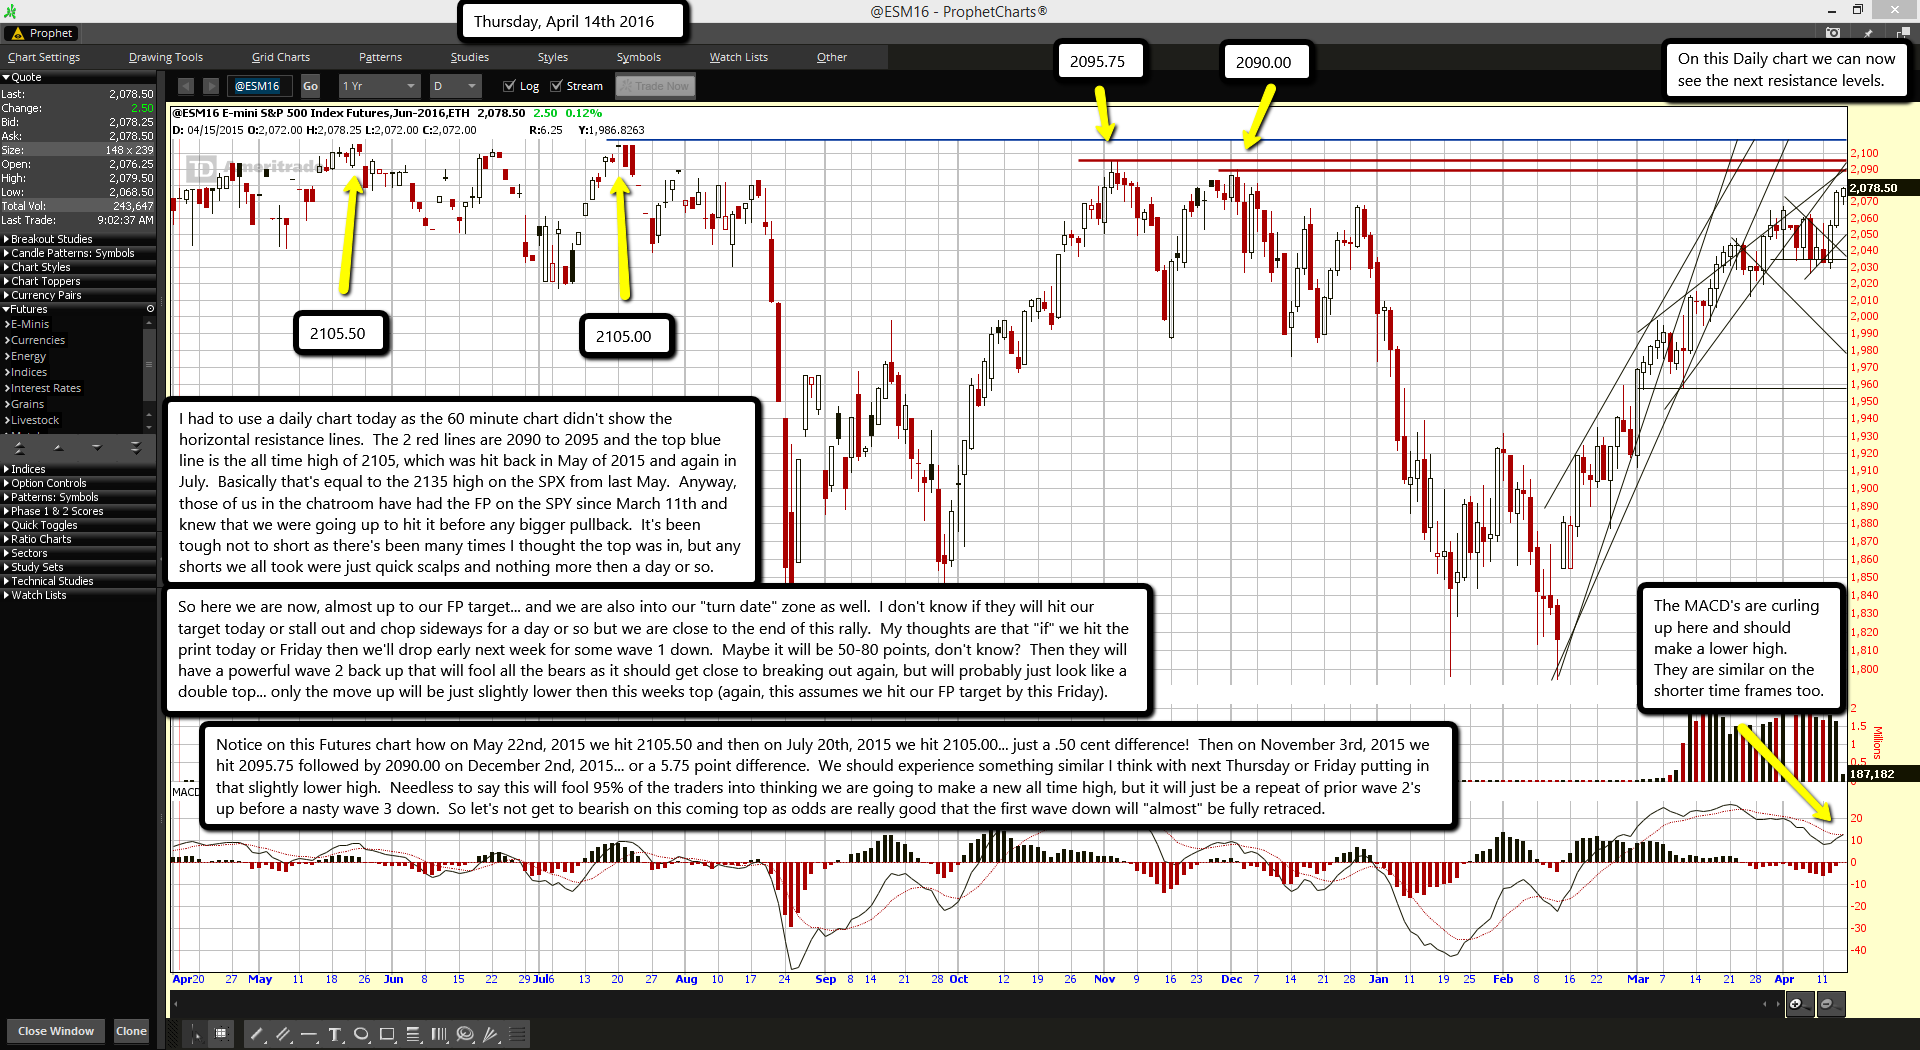
On this Daily chart we can now see the next resistance levels.

The MACD's are curling up here and should make a lower high.  They are similar on the shorter time frames too.

I had to use a daily chart today as the 60 minute chart didn't show the horizontal resistance lines.  The 2 red lines are 2090 to 2095 and the top blue line is the all time high of 2105, which was hit back in May of 2015 and again in July.  Basically that's equal to the 2135 high on the SPX from last May.  Anyway, those of us in the chatroom have had the FP on the SPY since March 11th and knew that we were going up to hit it before any bigger pullback.  It's been tough not to short as there's been many times I thought the top was in, but any shorts we all took were just quick scalps and nothing more then a day or so.

So here we are now, almost up to our FP target... and we are also into our "turn date" zone as well.  I don't know if they will hit our target today or stall out and chop sideways for a day or so but we are close to the end of this rally.  My thoughts are that "if" we hit the print today or Friday then we'll drop early next week for some wave 1 down.  Maybe it will be 50-80 points, don't know?  Then they will have a powerful wave 2 back up that will fool all the bears as it should get close to breaking out again, but will probably just look like a double top... only the move up will be just slightly lower then this weeks top (again, this assumes we hit our FP target by this Friday).

Notice on this Futures chart how on May 22nd, 2015 we hit 2105.50 and then on July 20th, 2015 we hit 2105.00... just a .50 cent difference!  Then on November 3rd, 2015 we hit 2095.75 followed by 2090.00 on December 2nd, 2015... or a 5.75 point difference.  We should experience something similar I think with next Thursday or Friday putting in that slightly lower high.  Needless to say this will fool 95% of the traders into thinking we are going to make a new all time high, but it will just be a repeat of prior wave 2's up before a nasty wave 3 down.  So let's not get to bearish on this coming top as odds are really good that the first wave down will "almost" be fully retraced.

Regulators reject plans of 5 big US banks for preventing another taxpayer bailout

0

This 2013 file photo shows the headquarters of JP Morgan Chase on Park Avenue in New York.

Federal regulators said Wednesday that five of the country’s largest banks, including JPMorgan Chase and Bank of America, still don’t have credible plans for winding down their operations without taxpayer help if they start to fail.These so-called “living wills” are a critical requirement of the 2010 financial reform package, Dodd-Frank, aimed at a preventing a repeat of the taxpayer bailouts that took place during the financial crisis. The regulators found various problems with the plans submitted by Bank of America, Bank of New York Mellon, J.P. Morgan Chase, State Street, and Wells Fargo.The failures are likely to tap into populist concerns that U.S. banks are still “too big to fail.”  It comes as the banking sector is likely to report weaker financial results for the first quarter of the year.

The five banks have until October to address the problems found by the Federal Reserve and the Federal Deposit Insurance Corporation. If the deficiencies aren’t addressed, the banks could face higher capital requirements or other regulatory sanctions if their plans are still not deemed sufficient.

“The FDIC and Federal Reserve are committed to carrying out the statutory mandate that systemically important financial institutions demonstrate a clear path to an orderly failure under bankruptcy at no cost to taxpayers,” Martin J. Gruenberg, chairman of the FDIC, said in a statement.

The findings come at a time when other measures put in place to respond to the financial crisis are also under assault. Regulators have also attempted to identify financial firms, outside of banks, that could pose a threat to the economy. These firms have traditionally received little government scrutiny, but after the massive insurance company AIG nearly collapsed in 2008 and required a $182 billion taxpayer bailout, lawmakers called for stricter oversight of this portion of the financial industry.

A government panel has labeled four firms — AIG, Prudential, General Electric’s financing arm and MetLife — as “systemically important financial institutions,” subjecting them to tougher government rules.

But General Electric is now arguing that it no longer qualifies for the designation because it has shrunk its balance sheet. And MetLife, which was founded in 1868 and has a global footprint of 100 million customers and a market capitalization of $48 billion, filed a lawsuit that now threatens the entire process.

Earlier this month, U.S. District Judge Rosemary M. Collyer overturned the company’s “too big to fail” label and challenged the process the government used.  The Treasury Department is appealing the ruling, which experts have said could hobble this portion of the financial reform law.

Source link

News About Obummercare Has Been Bad Lately. How Bad? – New York Times

0

Couples at Evergreen Health Care in Manassas, Va., signing up for Affordable Care Act coverage last November.

Ever since passage of the Affordable Care Act, a fierce debate has been waged over whether the law would work as advertised. While advocates promised that the design of new insurance markets would transform the way consumers buy health insurance, critics warned that the new market would never succeed. Reed Abelson and Margot Sanger-Katz have had front-row seats to the debate, and the two reporters took a few minutes to discuss when — and if — the market would stabilize.

Margot: It’s been a few weeks of bad news about the Obamacare marketplaces. On Friday, we learned that UnitedHealth has decided to pull out of Obamacare marketplaces in two states. The week before, the Blue Cross and Blue Shield Association put out a paper offering not-too-subtle hints that some members were losing money. Reed, you wrote recently about how surprising stasis in the employer insurance market means we can look forward to much smaller Obamacare marketplaces than most people expected when the health law passed. And the parade of struggling start-up insurer companies has extended to Maine’s Community Health Options, one of the co-ops that had long been held up as one of the most successful. Health insurers need to submit their rates to regulators in the next few weeks — or decide to exit markets. Should we be worried about a health insurance apocalypse?

Reed: I think people have a tendency to catastrophize, especially when it comes to Obamacare. UnitedHealth, which is one of the nation’s largest health insurers, has only reluctantly embraced the new market, and the company is always held up as an example of why the sky is falling and why Obamacare is going to crash and burn: If United can’t make it, no one can.

United has only a small fraction of the individual market, but some of the Blues are also struggling. What is most troubling is the fact that many insurers are losing money. You may not sympathize much with the insurance companies — and no one does — but they have to make enough money to pay claims. Do you think those losses are temporary — or a sign that the market is fundamentally unstable and potentially unsustainable?

Margot: I think some of both. It seems clear that some insurers just made pricing mistakes. I’d include a lot of the nonprofit co-op plans that have gone belly up in that category. United may fall in that category, too, in some places. That doesn’t seem to me like a permanent problem. If everyone priced too low, they can just raise their prices in future years, and it’ll be O.K. That’s not great for middle-class people who pay their own premiums, but most people in the exchanges won’t notice a difference because of the way the subsidies work.

These markets also turned out to be more complicated than some insurers expected. Some regulatory choices didn’t go their way. And it does look as if more customers than you might expect are staying enrolled in plans for only part of the year, which makes it hard for the insurers to collect premiums. But I think they’ll probably figure it out.

Reed: But isn’t it a vicious cycle? The big players won’t stay in markets unless they can attract enough customers to make it worth their while. Those who say Obamacare is doomed argue that the premiums are just too high for people who don’t qualify for a subsidy. If you are insured and relatively healthy, you may not feel as if the coverage is a good deal. The deductibles are steep, meaning you end up paying for a lot of your care before you see the first dollar of coverage, and you can’t always see your choice of doctor.

The result is that the market could be too small and therefore too volatile to attract mainstream insurers like United.

How do you solve that?

Margot: Well, it seems clear that you need some competition in every market to keep prices low. But maybe we don’t need the big carriers to play everywhere. As you noted, United barely showed up in the exchanges in the first place, and customers in most markets still have a lot of choices. The Medicaid-managed care plans seem to be having some success in this market, so maybe they will be a big part of the exchange mix.

I also think it’s worth looking at the states where things are going well and the insurers are making money: California, Vermont, Washington. Those state exchanges made some different regulatory choices early on that got more people into the new markets right away, so their markets stabilized more quickly.

Reed: You’re right that you may not need the established players for the market to work. The market may not look the way we thought it would, with the same insurers and same characteristics as the employer market. But one of the reasons insurers are leaving is because of the market’s instability. There’s tremendous churn in this market, with most people switching plans every year to try to find a cheaper alternative.

I’m not sure I know what the business model is for an insurer, if the expectation is that you’re going to keep your customers for only a year. It makes achieving long-term goals like keeping people healthier and focusing on preventive measures much harder because there may be no payoff for the insurer.

Margot: Yes, I think this is one of the contradictions of the Affordable Care Act’s design. The whole idea was that competition between the insurance companies would help to hold down prices, the way it does for, say, electronics or groceries. In order for that system to work, you need people to actually switch plans if their plan starts charging more than the competition. The fact that people are actually switching seems like a sign that this market is functioning as it was designed. But as you point out, all that churn sure makes it hard for an insurer to make money by investing in its customers’ long-term health. But the individual market, pre-Obamacare, also had a lot of churn.

Reed: Yes, there’s always been churn, but the insurers got pretty good at figuring out which people they wanted to insure by turning away the people who were most likely to cost them the most money. They definitely figured out how to make money.

It’s easier to smooth all of this out if you insure more people. Do you think there’s opportunity to see the market increase in size? I know insurers in the early years suffered when some states allowed people to keep their existing plans. Those plans that were grandmothered, as it is called.

Margot: My sense from talking to folks in the industry is that the grandmothered plans really wrecked their early calculations. The Obama administration, responding to a political freakout about people whose plans were getting canceled in 2014, let states keep them for a few more years. The result was that healthy people tended to hold onto their old, cheaper plans, while sick people went to the exchanges. You can see how that might make the exchange market unprofitable for new entrants.

I do think the market size is a bit of a chicken-or-egg question. Your story last week on stability in the employer market did such a good job of laying this out. Everyone (including the Congressional Budget Office) expected that employers would start dropping coverage once the marketplaces were up and running. That didn’t happen. It means that Obamacare has been much less disruptive to the status quo than many people thought. But it also means that the exchange markets are smaller and probably more expensive than people thought, too. If prices keep going up, maybe they’ll never grow much. It certainly seems like everyone is cutting down their long-term estimates for exchange enrollment.

Reed: The other possibility would be to expand the pool of people who qualify for subsidies. Is that a political nonstarter?
Source link

Coal giant Peabody Energy files for Chapter 11 bankruptcy

0

April 13 -- U.S. coal giant Peabody Energy filed for bankruptcy, the most powerful convulsion yet in an industry that's enduring the worst slump in decades.

Peabody Energy climate change settlement

The nation's biggest coal company, Peabody Energy (BTU), filed for Chapter 11 bankruptcy protection on Wednesday as the coal industry grapples with the fallout of low natural gas prices, costly regulations and legacy costs.

Peabody had warned in March that "sustained depressed" coal prices had placed it on the edge of insolvency.

The company also suffered a sharp blow from its exposure to the bankruptcy of former subsidiary Patriot Coal, one of several coal giants to topple into bankruptcy court over the last couple years.

Low natural gas prices, the sluggish Chinese economy and U.S. environmental regulatory pressure have compounded the financial pressures facing coal companies,which include costs such as pensions and retiree health care obligations, analysts say.

Peabody has posted four consecutive yearly losses, including a $2 billion loss in 2015 as revenue fell 17% to $5.6 billion.

The company listed $10.1 billion in debts and $11 billion in assets, including ownership interest in 26 active mines in the U.S. and Australia. Shareholders with at least 5% of the company are Blackrock, Kopernik Global Investors, Vanguard Group and Susquehanna Securities, according to a court filing.

"Through this process, the company intends to reduce its overall debt level, lower fixed charges, improve operating cash flow and position the company for long-term success, while continuing to operate under the protection of the court process," Peabody said Wednesday in a statement.

Trading of the company's shares (BTU), which closed at $2.07 on Tuesday, will be suspended. Two years ago, the stock hit a high of $299.10 in the first quarter of 2014.

"This was a difficult decision, but it is the right path forward for Peabody.  We begin today to build a highly successful global leader for tomorrow," CEO Glenn Kellow said. "This process enables us to strengthen liquidity and reduce debt, build upon the significant operational achievements we've made in recent years and lay the foundation for long-term stability and success in the future."

Peabody said it had secured $800 million in bankruptcy financing from a group that includes secured and unsecured creditors to maintain operations.

Peabody noted that the sale of assets in New Mexico and Colorado had collapsed after a prospective buyer could not complete the deal.

The company hired law firm Jones Day to provide bankruptcy counsel, investment bank Lazard for financial advice and FTI Consulting for restructuring guidance.

Source link

Mickey Mouse-shaped solar facility unveiled at Disney World

0

This April 3, 2016, photo provided by Walt Disney World, shows Disney's Mickey Mouse-shaped solar facility in Lake Buena Vista, Fla. Officials with Disney World, Duke Energy and Disney's private government, flipped on the switch to the Mickey Mouse-shaped solar facility on Tuesday, April 12, 2016. The Mickey Mouse-shaped solar facility is located on 22 acres near Epcot and is made up of about 48,000 solar panels. (Walt Disney World Photo via AP)

LAKE BUENA VISTA, Fla. (AP) - It’s only fitting that solar panels that will help with the power needs of Walt Disney World are shaped like the famous ears of the mouse that started the Disney enterprise.

Officials with Disney World, Duke Energy and Disney’s private government on Tuesday flipped on the switch to a Mickey Mouse-shaped solar facility located on 22 acres near the Epcot theme park.

The facility is made up of 48,000 solar panels and is operated by Duke Energy.

Duke Energy will sell the energy to Disney’s private government, Reedy Creek Improvement District.

In addition to helping power parts of Walt Disney World, the energy will be used to power hotels along Hotel Plaza Boulevard, as well as the Four Seasons Resort.

People rejoice over bridge grand opening

0

Virginia Street is officially open to commuters in downtown Reno, both pedestrians and drivers. It's been a long wait, but many say it was worth it. The bridge is ready to embrace the crowds that have avoided it for so long.

The wait is finally over; let the celebration commence!

"We love how the architecture sets off the post office. It's just a great view here," said one Reno Man.

"It's nice to have access to downtown without having to walk around," said a cyclist going through.

Hundreds gathered for the lighting ceremony, commemorating 10 months of hard work by bridge developers, and patience from commuters and business owners.

"People can see that the building hasn't been abandoned, business is still here and that they can get here," said Sandra Van-Scott, manager at Antique Angel Chapel.

Right next to the temporary cone zone, sits antique angel chapel. It's an example of what almost a year of construction can do to a surrounding business. Van-Scott says they lost about 60 percent of her clients.

"They had the big white cement blockades and the cement walls with the 7-foot plywood walls that went from one end to the other. Folks would come in and be upset with us thinking we closed it off and that we had a magic door that would go under the river and get to the other side," said said.

You can say, it's all water under the bridge now, Just in time for wedding season.

"I'm glad we made it through, I'm glad the bridge opened early," said Van-Scott. "I'm really happy things will be back to normal."

With a wider side walk for pedestrians and a bike lane for cyclists, the Virginia Street Bridge also added artwork along a landing that takes you straight to Truckee River.

Businesses surrounding the are especially excited for summer events, like the wine walks and beer crawls, hoping the bridge will bring more foot traffic into their buildings.

Source link

IRS Admits It Encourages Illegals To Steal Social Security Numbers For Taxes

0

This isn’t exactly the kind of story the IRS wants buzzing around at tax time. The IRS and Justice Department normally want ‘scared straight’ stories just before Tax Day. Ideally, when an indictment or conviction for tax evasion hits the news, it makes you think twice. Somehow, you think just a bit more about all those deductions, or if you really reported all your income, before you sign your return under penalties of perjury.

Instead, we have the top dog at the IRS, the IRS Commissioner himself, admitting that, well, there’s a problem with illegal immigrants and taxes. In fact, the top IRS official this time wasn’t talking about how the IRS wipes some hard drives or can’t find emails. He wasn’t even asking for a bigger budget to give bonuses to IRS employees.

The 9 Most Common Tax Filing Mistakes

This time, he was talking about illegal immigrants, and about the IRS turning a blind eye. Or maybe worse. The IRS actually wants illegal immigrants to illegally use Social Security numbers, he suggested. IRS Commissioner John Koskinen made the surprising statement in response to a question from Sen. Dan Coats, R-Ind., at a Senate Finance Committee meeting. The question was a touchy one. Gee, is the IRS collaborating with taxpayers who file tax returns using fraudulent information? It wasn’t put exactly that way. According to Senator Coats:

What we learned is that … the IRS continues to process tax returns with false W-2 information and issue refunds as if they were routine tax returns, and say that’s not really our job. We also learned the IRS ignores notifications from the Social Security Administration that a name does not match a Social Security number, and you use your own system to determine whether a number is valid.”

Commissioner Koskinen was asked to explain this. He suggested that as long as the information is being used only to fraudulently obtain jobs, the IRS was OK with it. In fact, he said that the IRS actually had an interest in helping the illegal immigrants to crook these rules. In fairness, perhaps it’s just the ‘that’s not my department’ response that abounds in big government. Perhaps this just isn’t the IRS’s problem, but it sure seems odd to have any agency chief encouraging illegal immigrant theft of SSNs.
Source link

House committee unveils Puerto Rico rescue bill with time running out

0

A new draft of legislation to rescue Puerto Rico from the jaws of a debt crisis was released by the House Committee on Natural Resources on Tuesday evening, as the territory’s governor warned that his government did not have enough money to pay for fuel for school buses or police patrol cars, or for therapists for schoolchildren with special needs.

The revised bill includes a provision for a vote by two-thirds of creditors on any particular debt restructuring proposal — a major change that was designed as a concession to conservative Republicans and would give Puerto Rico’s creditors leverage to insist on voluntary settlements.

The threshold is low enough to give a newly created oversight board the power to impose restructuring deals on reluctant creditors, but it it is high enough to potentially bog down restructuring talks.

If the oversight board fails to get the support of two-thirds of creditors, it can turn to a judicial procedure to enforce a settlement.

Rep. Rob Bishop (R-Utah), the committee’s chairman, said in a news release that the bill offers “tools to redirect Puerto Rico from a path of destitution towards a path of prosperity.”

“This is the constitutionally-sound solution that will provide real, long-lasting reform to the Commonwealth while respecting the rights of all parties and creditors,” he said. “It is the island’s best shot to mitigate its financial collapse and future calls for a bailout, which would be untenable.”

House Speaker Paul D. Ryan (R-Wis.) endorsed the bill shortly after its release Tuesday, saying it “protects American taxpayers from bailing out Puerto Rico.” But it was not clear in the hours after the bill’s release whether it would ultimately win the endorsement of the Republican Study Committee (RSC), the influential group of House conservatives that includes most GOP members.

The group’s chairman, Rep. Bill Flores (R-Tex.), said in an interview Tuesday that he had not reviewed the final text of the latest draft but said there appeared to be improvements. “In a perfect world, I’d like to see there can’t be an involuntary cram-down,” he said. “But if we can find a way where there’s a good likelihood of having a consensual restructuring, maybe I can find happiness on this.”

The RSC balked at the previous version of the legislation, casting doubt on whether any Puerto Rico bill could garner the support of a majority of House Republicans — a key threshold for Ryan, who has vowed to abide by the wishes of his party conference. Outside activist groups, notably Heritage Action for America, also have pressured Republicans to reject strong restructuring provisions and require more sweeping economic reforms.

But the bill probably will need Democratic support to pass, and House Minority Leader Nancy Pelosi (Calif.) and other key Democrats have been engaged with the bill’s Republican drafters to address concerns about the powers of the control board created under the legislation.

Those changes included increasing the size of the control board, and changing its political composition and limiting its non-fiscal powers — modifications made, in the words of a Republican committee summary, “to address concerns that it was too colonialist.”

Gov. Alejandro Javier García Padilla, in Washington with a broad delegation of legislators and business people from Puerto Rico, stressed the need for haste. He said that “we are in a humanitarian crisis” and that about 10,000 children have not been able to attend school because of a lack of fuel for buses.

García Padilla said that Puerto Rico’s government owes close to $2 billion to private suppliers of goods and services and that the arrears will climb to $2.2 billion by June 30, when the territory expects to default on its general obligation bonds, considered the safest type of bonds for investors.

The governor called the new version “a step in the right direction.” Earlier, he sharply criticized the first draft of legislation to help Puerto Rico restructure its crushing debt of about $72 billion; that draft created a five-person appointed board to root out waste and corruption, set the island’s budget on a sustainable track and restructure the territory’s debts.

García Padilla said that the board’s structure would be “turning Puerto Rico back to 1900 . . . after the invasion and Spanish American war.” He said “it will make no sense” because it would create a financial control board with the power to impose taxes, fire people from jobs and curtail services without regard to democratically elected officials in Puerto Rico.

But he said the new version of the legislation “incorporates some of our comments with respect to a more balanced calibration of the Board’s powers.”

Some of the investors in Puerto Rican bonds oppose the creation of any bankruptcy-like procedure that could impose a final settlement on a minority of holdout creditors.

A group called the Center for Individual Freedom has spent about $200,000 on television ads in the Washington market, according to the Sunlight Foundation. The ads urge people to “tell Congress” to “stop the Washington bailout of Puerto Rico” — even though the House draft of legislation does not provide any money for Puerto Rico. The Alexandria, Va.-based 501(c)(4) group says on its website that its “mission [is] to protect and defend individual freedoms and individual rights guaranteed by the U.S. Constitution.”

On Monday, Puerto Rico’s government sweetened a January offer to pay creditors, offering to boost its debt-service payments to $1.85 billion a year, up from $1.7 billion a year in the earlier offer. Those payments would equal about 15 percent of projected government revenue in 2021, a level higher than in virtually all mainland U.S. states.

The government also said that an earlier proposal for a “growth bond” that would depend on a certain level of economic growth in Puerto Rico would be replaced with a “capital appreciation bond” that would require payments regardless of economic growth.

But investors would still end up taking deep reductions in the overall payments they are owed.

Last week, Puerto Rico declared a debt moratorium, allowing the governor to temporarily halt debt payments by government and public corporations or impose a stay on bondholder litigation. The moratorium would block a $422 million debt-service payment by the Government Development Bank on May 1, forcing a default.

The credit rating agency Moody’s said in a statement Tuesday that the moratorium “signals the culmination of the US territory’s liquidity crisis and the complexity of negotiating restructuring agreements with holders of the Commonwealth’s debt.”

Steven Mufson covers the White House. Since joining The Post, he has covered economics, China, foreign policy and energy.

Mike DeBonis covers Congress and national politics for The Washington Post. He previously covered D.C. politics and government from 2007 to 2015.
Source link

s2Member®